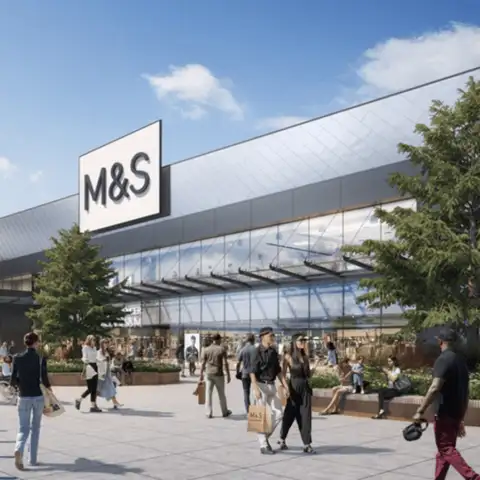
British Land has bought the 192,000 sq ft Telford Bridge Retail Park in Shropshire for £30 million, announced alongside a first-quarter trading update on 14 July 2026 covering the three months to 30 June.
Outgoing chief executive Simon Carter framed the quarter simply: "Both of our core markets remain strong. Demand continues to outstrip supply across... retail parks, leasing remains ahead of previous passing rents, and forward indicators give us confidence that these favourable market conditions will persist." Carter hands over to Joanne McNamara in September.
On the arithmetic, £30 million for 192,000 sq ft works out at roughly £156 per square foot. Neither funding structure nor net initial yield was disclosed, so the return on this particular purchase cannot be established from the announcement alone.
What the update said
The quarter delivered 567,000 sq ft of leasing across campuses and retail parks combined, completed 4.8% ahead of estimated rental value (ERV) and 8.7% ahead of previous passing rent. A further 1.1 million sq ft is under offer, at 6.8% ahead of ERV and 15.9% ahead of previous passing rent.
Within the retail parks specifically, deals completed in the quarter plus those under offer were running 13.7% ahead of previous passing rent, which the company attributes to near-full occupancy and a portfolio that is "largely rack rented."
Guidance was reiterated in directional terms: like-for-like net rental growth at the top end of the 3-5% target range, and 3-5% ERV growth expected across the portfolio. Carter described the exposure as one of the UK's most attractive real estate sectors, providing "a strong platform for continued EPS growth," with occupational strength underpinning the FY27 earnings outlook.
Reading the three numbers
The three headline measures say materially different things about the same portfolio.
ERV is the valuer's estimate of open market rent. Leasing ahead of ERV is the most informative disclosure here, because it shows occupiers paying more than the assumed market rent — evidence that demand is exceeding the pricing model rather than merely meeting it.
Passing rent is what tenants pay today. Beating previous passing rent on renewal shows the gap to market is being closed, but in a near-full, largely rack-rented portfolio much of that gap has already been captured. Rack rented means contracted rents already sit close to market levels, leaving limited embedded reversion to release later.
Like-for-like net rental income isolates growth from the existing asset base. That figure at the top of a 3-5% band is the durable indicator, which is why the 13.7% number should be read carefully: transactional premiums flatter, like-for-like does not.
Why retail parks rather than high streets
British Land's core markets are campuses and retail parks, and the second of those has quietly become one of the more reliable segments of UK commercial property.
Three characteristics explain it. Units are large, standardised and cheap to fit out, so occupancy costs suit national retailers that still require a physical footprint. Tenant demand has consolidated around occupiers — discount food, home improvement, automotive, drive-through and healthcare-adjacent uses — that are less exposed to discretionary spending swings than fashion. And critically, supply has not responded: new retail park development has been minimal for years, competing uses such as logistics absorb available land, and consent for out-of-town schemes has become harder to obtain.
Scarcity plus stable tenant covenants produces exactly what the update describes: occupancy near full, rents already at market, and pricing power at renewal. None of that requires retail spending to grow; it requires the units to remain the cheapest route to customers.
Pipeline versus signed deals
One caveat is worth stating plainly. The 1.1 million sq ft under offer is roughly double what was completed in the quarter, and at a wider premium on both measures. That is a strong forward indicator, but it is not contracted income. "Under offer" generally means heads of terms agreed or solicitors instructed, and a proportion will not convert.
Neither should the widening premium be read purely as momentum. Later-stage deals skew toward units that already had competitive tension, and mix effects — a few large schemes — can move averages materially at this volume.
A second disclosure limitation is structural: the leasing figures combine campuses and retail parks. The company reports strong pricing across both, but neither segment's contribution is broken out, so the campus figures cannot be assessed independently.
The acquisition in context
Telford Bridge is a bolt-on rather than a transformational purchase — a single asset bought into a portfolio already performing well. That framing matters, because the strategic question is why management is deploying capital outward at this point rather than recycling it.
The plausible answer is that if leasing is transacting ahead of ERV, acquiring assets where rents sit below achievable market levels becomes accretive quickly. The risk is that the same pricing environment inflates what buyers pay, leaving less of the reversion for the new owner. Without disclosed yield or income, it is not possible to judge which side of that line this asset falls on.
What to watch
- Whether the 1.1 million sq ft under offer converts at the stated premiums, or whether completed deals converge back toward the 4.8% ERV figure once signed.
- Which asset was funded and how — recycling lower-yielding stock, or incremental debt — since that determines whether this is accretive or merely additive.
- Occupancy at the next update. At near-full levels, further gains are constrained, so the metric to watch is subtle: lease events where the re-letting spread is captured, not occupancy itself.
- Whether ERV growth of 3-5% survives into the second half, since expectational guidance of this kind reacts quickly to changes in tenant demand.
- The handover to Joanne McNamara in September, and whether strategy shifts toward acquisition, development or capital allocation.
Sources
- British Land Q1 FY27 trading update, three months to 30 June 2026, issued 14 July 2026: 567,000 sq ft leased (4.8% ahead of ERV, 8.7% ahead of previous passing rent), 1.1 million sq ft under offer (6.8% and 15.9% respectively), retail park deals 13.7% ahead of previous passing rent, near-full occupancy, portfolio largely rack rented, like-for-like net rental growth at the top of the 3-5% range, 3-5% expected ERV growth; quotes from Simon Carter.
- Acquisition: 192,000 sq ft Telford Bridge Retail Park, Shropshire, £30 million.
- Note: the £156 per square foot figure is the author's calculation from those two numbers. Analysis of ERV mechanics, rack-rented reversion, supply constraints and the cautions above is the author's; the chief executive succession to Joanne McNamara is as stated in the same update and has not been independently verified here.