Nigerian underwriter Cornerstone Insurance Plc has reported insurance revenue growth of 34% for the 2025 financial year and recommended a dividend of N0.28 per share, while headline profit fell sharply from the prior year's level.
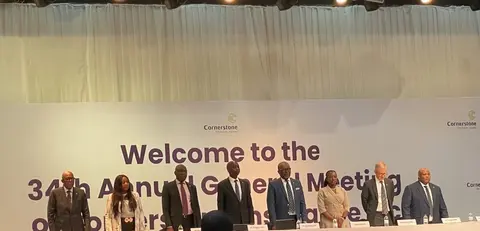
Speaking at the company's 34th Annual General Meeting in Lagos, Acting Chairman Afolabi Balogun said the group recorded insurance revenue of N51.66 billion for the year ended 31 December 2025, implying roughly N38.6 billion in the prior year from the stated 34% growth. Total assets rose to N141.03 billion and shareholders' funds to N72.86 billion from N60.50 billion in 2024.
The apparent contradiction in those two sentences — record top line, sharply lower profit — is the whole story, and it is explained by what was in the 2024 comparison.
The prior-year base
Profit after tax came in at N11.76 billion, compared with N25.89 billion in 2024. Managing Director Stephen Alangbo said profit before tax declined to N8.73 billion from N28.62 billion, following exceptional foreign exchange gains recorded in the previous year.
Those gains were large. The company posted N30.83 billion in one-off foreign exchange gains in 2024 following the naira devaluation. Strip that item from the 2024 pre-tax figure and the underlying position was roughly N2.2 billion below zero.
Set against that restated base, N8.73 billion of pre-tax profit in 2025 represents a substantial improvement in operating performance rather than a deterioration. Alangbo made that argument directly: "Adjusting for this one-off effect, our underlying performance demonstrates sustained growth in our core insurance operations."
The caution is that this is a comparison against a reconstructed number. FX gains are real and cash-received; they should not be treated as noise. But they should also not be treated as underwriting performance, which is the point management is making.
Two things to note in the numbers
Profit after tax of N11.76 billion exceeds profit before tax of N8.73 billion, implying a net tax credit of roughly N3 billion. Without the detailed tax note, the composition cannot be established — a deferred tax credit, prior-year adjustments or other items could account for it. It is the kind of line that deserves a question at the AGM, because it means reported earnings are being supported below the tax line.
Second, shareholders' funds grew by about N12.4 billion, or roughly 20%, while retained earnings alone would not obviously produce that increase given the profit decline and the dividend. Other comprehensive income, reserve movements or revaluation effects are plausible contributors; the split is not disclosed here.
What insurance revenue does and does not tell you
"Insurance revenue" is a specific measure under IFRS 17 rather than gross premium written. It recognises revenue as coverage is delivered, net of the portion attributable to investment and other components, so it is not a cash measure and it is not directly comparable with the premium figures of earlier years.
That distinction matters here. A 34% increase in insurance revenue is evidence that the book is growing and is being recognised faster; it is not evidence that cash premiums collected rose by the same amount, nor that claims experience improved. For an insurer, the three things that determine whether growth is real are the combined operating ratio, investment income quality, and claims reserve development. None is disclosed alongside the headline.
The dividend
The board recommended N0.28 per share against earnings per share of 64 kobo, which implies a payout of roughly 44%. For a Nigerian insurer that is a reasonable balance: sufficient to signal confidence, leaving enough retained to support expansion without straining capital.
Capital retention is the more pressing consideration. Nigerian insurers have been operating against the backdrop of reform aimed at raising minimum capital requirements across the industry, and the specifics and timetable should be checked against current regulator guidance rather than assumed. In that environment, a 20% increase in shareholders' funds to N72.86 billion is a more strategically important line than either the revenue or the profit figure, because it determines what the company can write next.
The read
Balogun framed the results as reflecting "the strength of its franchise, the quality of its customer relationships, and the disciplined execution of our strategy," adding that Cornerstone enters this new phase "from a position of strength" with a clear strategy, strengthened capital base and experienced leadership team, alongside the support of a committed majority shareholder and a trusted brand.
On the numbers disclosed, the revenue growth supports the first half of that claim and the balance sheet growth supports the second. The unresolved question is whether profitability excluding the tax effect and excluding one-off items is genuinely improving, or whether 2025 simply looks better than a distorted 2024 because the distortion has been removed.
For investors, the answer will come from three disclosures rather than the headline: the tax note reconciling a N3 billion credit, the split between comprehensive income and retained earnings in shareholders' funds, and whether FX gains reappear in either direction this year.
Sources
- Statements at Cornerstone Insurance Plc's 34th Annual General Meeting, Lagos: Acting Chairman Afolabi Balogun on insurance revenue of N51.66 billion (up 34%), total assets of N141.03 billion, shareholders' funds of N72.86 billion (from N60.50 billion), profit after tax of N11.76 billion (from N25.89 billion), earnings per share of 64 kobo and the N0.28 dividend recommendation.
- Managing Director Stephen Alangbo on profit before tax declining to N8.73 billion from N28.62 billion, and on the N30.83 billion of one-off foreign exchange gains recorded in 2024 following naira devaluation; quoted remarks on underlying performance in core insurance operations.
- Nigerian Exchange filing: Cornerstone Insurance Plc audited FY 2025 results and earnings release (June 2026), which reports group profit after tax of N11.7 billion for the year ended 31 December 2025.
- Note: the 2024 revenue figure implied by the 34% growth rate, the implied N3 billion tax credit, the roughly N2.2 billion negative pre-tax position after removing the 2024 FX gain, the 20% increase in shareholders' funds and the ~44% payout ratio are the author's calculations or approximations. Analysis of IFRS 17 insurance revenue, capital requirements and the disclosure gaps identified is the author's, not the company's.