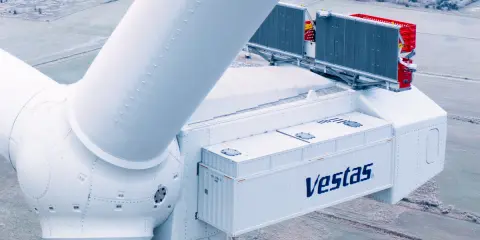
Vestas just recorded its best day in well over a decade thanks to a "rare combination" of factors that sent its share price stratospheric.
The Danish wind turbine giant saw its share price leap a staggering 19.66% by the close of business on the Nasdaq Copenhagen.
In real terms, the value of Vestas shares leapt from Dkr 197.05 ($30.40) at the start of business to Dkr 211.80 ($32.68) by its close. That price has largely held so far today, ticking down just 1% at time of writing.
Vestas achieved 26% revenue growth to €4.7bn and it now expects an earnings before interest and taxes (Ebit) margin of 7-9% before special items. That is up from a margin of 6-8% previously expected.
Vestas chief executive Henrik Andersen said Vestas is still aiming for 10% Ebit margin or better, but not this year.
Andersen has masterminded the turbine maker's recovery after it was rocked along with the rest of the Western wind industry by the economic fallout of Russia's invasion of Ukraine in 2022.
Vestas has only had nine days with a higher share price higher than yesterday's in the last four years, the most recent of those being in December 2023, when it hit Dkr 214.3.
And the last day the Vestas share price jumped by more than 19.66% was all the way back in 2012.
"This looks like a re-rating of Vestas rather than simply a reaction to one strong quarter," said Kristian Ascanius Jacobsen, managing director of Danish offshore wind consultancy Green Ducklings.
"The critical surprise is profitability: a 9.4% margin, a broad beat across the business and an upgrade to full-year margin guidance give investors much more confidence that the operational recovery is real."
"When you combine that with stronger orders and a sizeable buyback, there are positive surprises on earnings, outlook and capital returns simultaneously."
Vestas' order backlog has risen to 3.35GW, up 67% year-on-year. The value of that backlog is €37bn. The turbine-maker also launched a new €400m share buyback that will run until the end of the calendar year.
This represents a "rare combination" of good news for investors, said Jacobsen, "and probably explains why the share-price response has been so outsized."
'US paradox'There is another perhaps less expected driver for the excellent Vestas results - strong demand from the US.
This strong demand was the driver for its increase in order intake, said Vestas, which did not bag any offshore orders during Q2.
This strong performance in the US "highlights an interesting paradox" in the country's energy market, said Jacobsen.
"The Trump administration has been openly hostile to wind power, particularly offshore wind, yet the underlying demand for electricity is moving in the opposite direction."
"Data centres, AI and the electrification of the economy are creating an enormous need for new generation capacity, and in many parts of the US onshore wind remains one of the fastest and most competitive ways of adding power to the grid."
Trump's attacks on the sector are having an effect. Recent figures showed the US suffered its slowest quarter for wind installations since 2018. But Vestas has this year alone bagged 1.3GW of orders in the country for 'undisclosed projects,' with the turbine maker having taken to keeping its customers in the country quiet amid political attacks.
"So political rhetoric may be turning against renewables, but the economics of electricity demand are still creating a significant market for wind turbines," said Jacobsen.
"Vestas is benefiting from that disconnect: its improved profitability and strong order intake suggest that commercial demand can remain surprisingly resilient even in a much less supportive political environment."